
Zip
- Rating
- 4.7
- Downloads
- 5.00M
- Content Rating
- Everyone
Zip - Screenshots
Pros
- Quickly compresses and extracts common ZIP archives.
- Supports browsing files directly within the app.
- Useful for sharing multiple files as one archive.
- Simple interface that is easy for beginners to understand.
- Can help reduce storage use when compressing suitable files.
Cons
- Compression results vary greatly depending on file types.
- Large archives may take noticeable time to process.
- Some advanced archive formats may require extra support.
- Ads or optional purchases may affect the free experience.
- You should review permissions before opening downloaded archives.
Zip - Description
- App Name
- Zip
- Package Name
- com.quadpay.quadpay
- Developer
- Zip, Co.
- Category
- Shopping
- Last Updated
- May 24, 2019
- Version
- 1.252.1
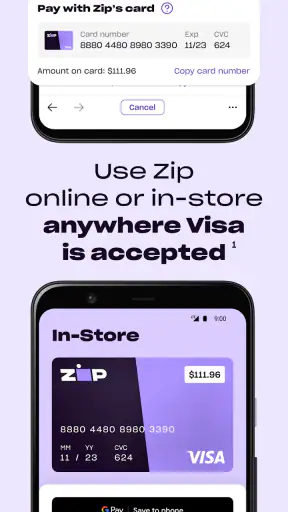
Zip is a shopping app from Zip, Co. that I would describe as a payment companion rather than a traditional marketplace. Its main purpose is to let me use flexible payment terms when shopping with participating merchants, including places where Visa is accepted. That distinction matters from the first tap: I am not opening it to browse a huge catalog inside the app, but to make a purchase more manageable at checkout.
After spending time with it, I found the appeal easy to understand. The app can be useful when I already know what I need and want another way to organize the payment. It is less compelling if I prefer to pay everything immediately, dislike managing scheduled obligations, or want one app that compares products and prices for me. Zip works best when I treat it as a budgeting tool for a planned purchase, not as permission to spend without a plan.
What to expect before using Zip
The first thing I noticed is how different Zip feels from ordinary shopping apps. A standard retailer app usually keeps the product search, cart, checkout, delivery information, and order history in one place. Zip sits closer to the payment stage. I still need to choose the retailer and the item, then use Zip where the payment option is available. That makes it especially practical for a purchase I have already researched.
The app is free to install, and its Everyone content rating makes it approachable for a broad audience. It has built a substantial user base, with more than five million installs and a 4.7 average from roughly 107 thousand ratings. Those figures suggest that the basic idea is easy for many shoppers to understand, although popularity should not replace reading the terms shown for an individual purchase.
In everyday use, the important question is not simply “Can I buy this?” but “What will this purchase mean for my upcoming budget?” Flexible payments can make a necessary item easier to handle, yet they can also make several separate purchases feel smaller than they are. I recommend deciding on a total spending limit before opening a retailer, rather than letting the available payment option determine the size of the cart.
A realistic example would be replacing a household item after an unexpected breakdown. I might compare the product at a retailer, check the complete checkout total, and then use Zip if the purchase fits my monthly plan. The useful part is having a payment route available at the moment I need it. The risky part is forgetting that the purchase still represents a real commitment after the excitement of solving the immediate problem has passed.
Zip is not automatically the cheapest way to shop. A debit card or ordinary credit card may be simpler for someone who already has the money set aside. A retailer’s own payment plan may be better when it offers clearer terms for that specific item. A credit card can also provide a familiar statement and established controls, while Zip may appeal more to someone who wants a separate shopping-payment workflow. The right choice depends on clarity, timing, and how confidently I can keep track of future payments.
Who is likely to benefit
I see the strongest fit for shoppers who plan purchases carefully, want flexibility at checkout, and are comfortable reviewing each payment obligation before confirming. It can also suit someone who shops across different retailers and prefers not to depend on one store’s financing system. The ability to use the service where Visa is accepted gives the app a broader role than a payment plan tied to one merchant.
On the other hand, I would skip it if I often lose track of subscriptions, bills, or installment commitments. I would also be cautious if my income changes from week to week and there is little room for an unexpected deduction. In that situation, paying with money already available may be less convenient in the moment but safer overall. Zip cannot remove the underlying cost of an item, and it should never be used to disguise an unaffordable purchase.
Getting started without making the first purchase confusing
My advice is to install Zip when I have a specific shopping task in mind, not simply because a flexible payment option sounds useful. Before opening it, I would write down the item, the retailer, the full expected total, and the amount I can comfortably commit. This small preparation changes the experience from browsing for something to buy into solving a defined problem.
The app is currently listed as version 1.252.1 and requires Android 8.1 or later. On a supported device, the initial setup should be approached as an account and payment-readiness step. I would keep my personal and payment details accurate, use an email address I check regularly, and read every screen rather than tapping through quickly. The most important information is the repayment schedule and the total obligation attached to the purchase.
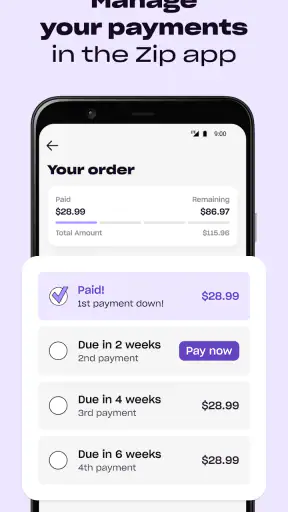
One useful habit is to take a moment after setup to understand where the app shows active purchases and upcoming payments. I would not rely only on memory or on a notification appearing at the perfect time. If the app presents a schedule, I would compare it with my calendar or banking routine. That extra check is more valuable than rushing toward the first checkout because it gives me a second place to notice a payment before it becomes urgent.
Another practical tip is to start with a modest, planned purchase rather than testing the service on a large discretionary order. A smaller first transaction lets me learn how Zip fits into my personal budgeting habits. I can see how I receive confirmations, how I recognize the payment schedule, and how I prefer to monitor the remaining obligation without putting unnecessary pressure on my finances.
I would also keep the retailer’s checkout open only after confirming that the item, shipping details, taxes, and final total are correct. Flexible payment tools can make the payment selection feel like the main event, but the product details still deserve attention. A low initial amount does not mean the overall transaction is low-cost. Checking the final total before choosing a payment option prevents a surprisingly common mistake: evaluating affordability from the first figure rather than the complete order.
Making the first successful purchase
The first meaningful success with Zip is not merely installing the app. It is completing a purchase while understanding exactly what happens afterward. I would begin at the retailer where I want to shop, add the intended item, and proceed until the payment choices are visible. If Zip is available for that checkout, I would select it and review the displayed terms before confirming.
The phrase “where Visa is accepted” gives the service useful reach, but I would still look for Zip’s payment option at the actual checkout. Acceptance in principle does not mean every retailer, item, order type, or transaction will behave identically. If the option does not appear, I would not repeatedly rebuild the cart or assume that a technical problem is the only explanation. I would use the retailer’s normal payment method or choose another store after checking the total cost.
During confirmation, I would verify three things: the merchant, the exact purchase amount, and the schedule of future payments. I would then save the confirmation in the same place I keep other important purchase records. This is a simple but non-obvious improvement to the experience. If I later need to match a charge with an order, having the retailer receipt and the Zip confirmation together is much clearer than searching through unrelated messages.
Once the purchase is complete, I would return to the app and make sure the transaction is visible in the account area. I would not assume that a successful retailer screen tells me everything I need to know about the payment arrangement. The app is most useful when I use it as the place to review the active commitment, not just as a button I press once and forget.
For a first-time user, this workflow answers an important practical question: do I need to shop inside Zip? In my experience, I would think of it as a route to payment that can support shopping elsewhere, rather than as a replacement for every retailer’s own app. That makes the process straightforward once I stop expecting a conventional product-browsing experience.
Where new users can get tripped up
The biggest source of confusion is the difference between flexible timing and a discount. Zip may change how a purchase is paid, but that does not automatically reduce the price of the product. I would compare the final retailer total with the same item elsewhere and then consider the payment terms separately. A convenient schedule should not distract me from shipping costs, taxes, returns, or a cheaper alternative.
A second point is that approval or availability at one moment should not be treated as a permanent shopping budget. I would review the terms shown for each new purchase and avoid assuming that a previous transaction guarantees identical treatment later. Payment products can depend on the transaction context, so the safest approach is to read the current checkout rather than rely on what happened last time.
Returns also deserve deliberate handling. If I send an item back, I would keep the retailer’s return confirmation and continue checking the payment activity until the purchase is properly reflected. I would not simply stop watching the schedule because the parcel is on its way back. The retailer and the payment service may each have a role in updating the transaction, and keeping both records makes it easier to spot a mismatch.
Another easy mistake is stacking several small purchases. One order may feel manageable, but multiple active plans can create a crowded payment calendar. My practical rule would be to count the combined future amount before confirming a new order. I would also avoid using Zip for routine impulse purchases simply because the first payment appears comfortable. The app’s convenience is strongest when it supports a decision I already made, not when it creates the decision.
Security and account access should be treated seriously as well. I would use a strong, unique password, protect the device itself, and review account activity regularly. If a payment or purchase looks unfamiliar, I would act promptly through the appropriate support and account channels rather than waiting for the issue to resolve on its own. These habits are not unique to Zip, but they matter more when a single app is connected to shopping activity and payment information.
Using it more thoughtfully after the first order
After the first purchase, I would turn Zip into a checkpoint in my shopping routine. Before every order, I would ask whether I need the item now, whether the complete price is competitive, and whether the future payment dates fit around rent, utilities, and existing commitments. This three-question pause takes little time and prevents the app from becoming a reason to buy before planning.
One advanced workflow I found useful is separating “planned flexibility” from “emergency flexibility.” For a planned purchase, I can compare retailers, wait for the right item, and decide whether the payment schedule genuinely helps. For an urgent purchase, I should first check whether I have another safe way to pay and whether the item can be repaired, borrowed, or delayed. The distinction keeps a stressful situation from turning into an automatic financing decision.
I would also review completed purchases periodically instead of looking only when a payment is due. This gives me a more honest picture of how often I use flexible payment terms and whether they are helping my budget or merely postponing pressure. If I notice that I am using Zip for everyday wants, carrying several obligations, or feeling anxious about upcoming payments, that is a clear signal to pause and return to simpler payment methods.
The app’s free price makes trying it easy, but “free” should be understood as the cost of downloading the app, not as a promise that every transaction has no cost or condition. I would read the current terms displayed for the specific purchase and avoid making decisions from the app’s installation price alone. This is one of the most important distinctions for a first-time user.
Zip’s developer is Zip, Co., and the app’s strong rating, around 57 thousand written reviews, and broad install base indicate that many people find the service useful. Still, reviews cannot tell me whether a particular payment schedule suits my income or whether a retailer’s return process will be convenient. I would use that general popularity as reassurance about familiarity, not as a substitute for checking my own numbers.
How Zip compares with familiar alternatives
Compared with paying directly by debit card, Zip offers more flexibility but requires more attention after checkout. Debit is usually easier when the money is already available and I want the purchase finished immediately. Zip becomes more attractive when timing matters and I can confidently manage the resulting schedule. The trade-off is convenience now versus an additional obligation later.
Compared with a traditional credit card, Zip may feel more focused on individual shopping payments, while a credit card can consolidate spending into a familiar statement. Some shoppers may prefer that single monthly overview; others may appreciate keeping a purchase arrangement separate. I would choose based on which system I am more likely to monitor accurately, not on which one makes the first payment look smaller.
Compared with a retailer’s own financing option, Zip can be more useful when I shop at different stores and want a consistent payment companion. A store-specific plan may be better when its terms are clearer for that product or when its returns and financing records stay in one place. I would compare the complete obligation, not just the wording of the payment button.
Compared with a conventional shopping marketplace, Zip is less about discovering products and more about supporting the transaction. If I want recommendations, detailed product comparisons, delivery tracking, and a single retailer account, the store’s app may be the better starting point. If I already know where I want to shop and need a flexible way to pay, Zip has a clearer role.
My recommendation for a first-time user
I recommend trying Zip only after choosing a specific purchase and confirming that the full cost belongs in the budget. Install it, complete the account setup carefully, check the payment terms at checkout, and record the transaction alongside the retailer receipt. That path leads to a meaningful first success without treating flexible payment as extra income.
I would recommend it to an organized shopper who wants payment flexibility across retailers and is willing to review each obligation. I would not recommend making it the default for every small purchase, or using it when the budget is already under strain. The app is most helpful when it creates breathing room inside a plan; it is least helpful when it encourages a plan that the budget cannot support.
With its free installation, Everyone rating, support for Android 8.1 and later, and current version 1.252.1, Zip is accessible to many people who want to explore this kind of shopping payment. My final view is positive but measured: it can be a practical bridge between wanting an item and paying for it over time, provided I remain fully aware of the total commitment. The best way to use Zip is to let my budget lead and let the app follow.
FAQ
What is Zip, and how does the app work?
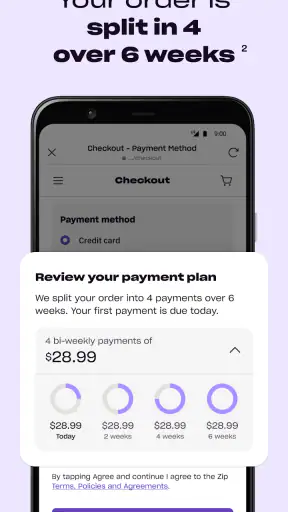
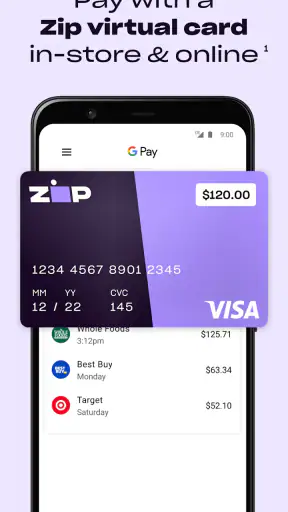
Zip is a buy now, pay later app that allows eligible users to split the cost of a purchase into several scheduled payments. You can use it at participating online and in-store merchants, either by selecting Zip during checkout or by creating a virtual payment method when supported. The app shows your repayment schedule, upcoming installments, and account activity in one place.
Who can use Zip, and what are the eligibility requirements?
Zip is generally available to users who meet the service’s age, residency, identity, and account requirements, although exact conditions may vary by country and product. Approval is not guaranteed, and Zip may review information such as your payment history, account details, and transaction amount. Before signing up, check the current requirements in your region and make sure your personal information is accurate.
Does Zip charge interest, fees, or other costs?
The cost of using Zip depends on the specific payment plan, merchant, and location. Some purchases may be advertised as interest-free when payments are made on time, while late fees, account fees, or other charges may apply in certain situations. Always review the final repayment amount, fee disclosures, and terms shown in the app before confirming a purchase.
What happens if I miss a Zip payment?
If a scheduled Zip installment fails, the app may retry the payment using your selected funding method, and additional fees or account restrictions could apply depending on your plan and local terms. A missed payment may also prevent you from making new purchases until the issue is resolved. Contact Zip support promptly if you expect a payment problem, rather than ignoring the notification.
Is Zip safe to use, and how can I manage my purchases?
Zip uses account security features and payment controls designed to help protect your information, but users should still use a strong password, enable available security options, and avoid sharing login details. The app lets you review orders, monitor upcoming payments, update payment methods, and contact support. Remember that buy now, pay later services are still credit-like commitments, so budget carefully before purchasing.


